Earn an 8% preferred return, secured by first-lien Texas real estate.
Matador Note Fund is a private real estate debt fund. Your capital funds short-term loans to vetted real estate investors — secured by a first lien on property worth more than the loan, paid out to you quarterly, targeting 8–12% total annual return.
No obligation. Accredited investors only · $50,000 minimum · Self-directed IRA eligible
Income that doesn’t depend on the stock market.
Most income options force a trade-off: bonds at 4–5%, or equities with all their volatility. Matador Note Fund is built for the space between — lending to experienced Texas real estate investors on short-term projects, secured by the property itself.
Traditional banks have pulled back from short-term real estate lending — slowed by regulation, rigid credit boxes, and long approval timelines. Experienced investors still need fast, flexible capital to acquire, renovate, and build. That gap is where private lenders earn premium, secured yield.
Matador has been filling that gap as an operating lender since 2019. The fund lets accredited investors own the lender’s side of the trade — interest income, quarterly, without picking stocks, managing tenants, or timing the market.
How your investment works
You invest
Verify accredited status and subscribe, starting at $50,000 — personally, through an entity, or via a self-directed IRA.
We deploy into first liens
Your capital is pooled and lent to vetted real estate investors on short-term loans secured by Texas property.
You earn quarterly
Borrowers pay interest. You receive the 8% preferred return each quarter — as cash, or reinvested to compound.
You keep flexibility
After a 24-month lock-up, request a withdrawal with 90 days' notice; redemptions process quarterly, subject to liquidity.
We get paid back first — and so do you.
Discipline is the product. Every loan is underwritten to protect principal before it chases yield.
First-lien position
The fund holds the senior recorded claim on the collateral, ahead of every other creditor. If a borrower defaults, we can foreclose to recover capital — the manager has done so four times across sixty Texas loans, with total principal losses under $50,000.
Conservative loan-to-value
65–75% weighted portfolio LTV target, with individual loans capped at 85%. The borrower's own equity absorbs the first loss, not yours.
Independently valued collateral
Third-party appraisals or broker opinions of value on every asset, plus title insurance naming the fund as insured and documented draw budgets.
Your preferred return comes first
Investors receive the full 8% preferred return before the manager participates in any profit. The manager only earns its share on the upside above yours.
Short duration
Loans run 6–24 months. The book turns over and re-prices to current rates far faster than long-dated bonds or buy-and-hold real estate.
Concentration limits
Once the fund holds $20M+, no single loan exceeds 20% of fund capital — so no one borrower or project can define your outcome.
What the preferred return pays.
The 8% preferred return is calculated on your invested capital and distributed quarterly. Here is the arithmetic on a $250,000 investment.
Illustrative arithmetic only. The preferred return is non-cumulative and is paid only out of the fund’s available distributable cash, at the manager’s discretion, as described in the PPM. It is not a guarantee, and it is not interest on a deposit. In a quarter with insufficient distributable cash, distributions may be reduced or not paid, and non-cumulative means an unpaid preferred return does not accrue for later payment. You may lose principal.
Built for capital that wants to work quietly.
Income seekers
Steady quarterly distributions with no properties to manage and no trades to time.
Self-directed IRA investors
Eligible for self-directed IRAs — asset-backed yield inside a retirement account.
Real estate investors
Own the lender's side of real estate without tenants, turnover, or capital calls.
Family offices
A disciplined first-lien credit allocation with transparent reporting and direct manager access.
Managed by a lender, not a marketer.
Matador Note Fund 1 LLC is managed by Matador Lending LLC — a Texas company founded in 2019 that originates mortgage loans and lends against Texas real estate. The fund is an extension of an operating lending business with sixty Texas loans behind it, not a first-time vehicle looking for its first deal.
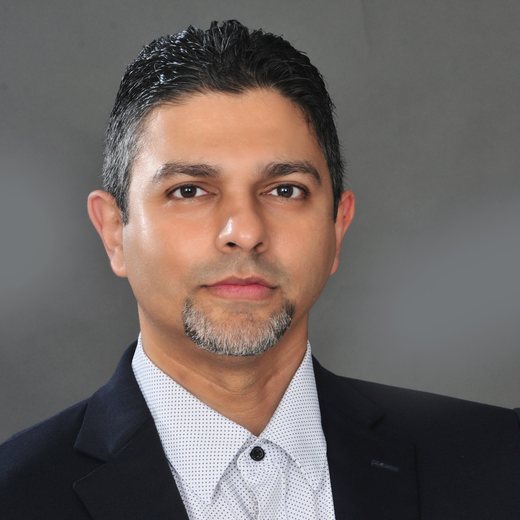
Apurva Sanghavi
Apurva has been in mortgage lending since 2001. He started in residential lending out of college and worked across the industry — loan officer, sales manager, and branch leader, setting top sales records at multiple mortgage companies. He was an early employee at real estate technology pioneer Trulia during its startup years.
Across his career he has overseen more than $1 billion in loan originations, and he is an active real estate investor himself — which is why the fund underwrites the way a practitioner would, not the way a spreadsheet would. He founded Matador Lending in 2019.
60 Texas loans. $13.3 million funded. Under $50,000 of principal lost.
Six years of lending in one number. The record below is the manager’s Texas book — loans funded by Matador Lending LLC and by Matador Note Fund 1 LLC, which has been lending since 2019. Same markets, same underwriting, and in many cases the same repeat borrowers.
since Oct 2019
funded
on those loans
(median 11)
repeat borrowers
What happened when loans went bad
Most fund pages explain how collateral protects you and then show nothing. Here is what happened when it had to work. Of 60 Texas loans, 55 repaid on schedule. Four went to foreclosure and one to a deed in lieu. Three of those five returned principal in full — one after the property was taken back and resold. Two came up short.
Total principal lost across six years and $13.3 million funded: under $50,000. Less than four tenths of one percent of everything lent.
That is what a first lien is for. It doesn’t prevent defaults — it decides what a default costs. The conservative loan-to-value target and the borrower equity sitting beneath every loan are why five workouts produced a rounding error instead of a hole.
(4 foreclosure, 1 DIL)
Representative loans
- Property
- SFR fix & flip
- Loan amount
- $415,800
- Term
- 6 mo
- Funded
- Jan 2022
- Outcome
- Repaid in full
- Property
- SFR fix & flip
- Loan amount
- $150,000
- Term
- 8 mo
- Funded
- Aug 2020
- Outcome
- Repaid in full
- Property
- Condo units (2)
- Loan amount
- $915,455
- Term
- 25 mo
- Funded
- Apr 2021
- Outcome
- Repaid in full
- Property
- Multi-family, 2–4 unit
- Loan amount
- $385,000
- Term
- 10 mo
- Funded
- Jun 2021
- Outcome
- Repaid in full
- Property
- New construction, SFR
- Loan amount
- $176,400
- Term
- 18 mo
- Funded
- Jan 2022
- Outcome
- Foreclosed · principal recovered
- Property
- SFR on 5.3 acres
- Loan amount
- $363,358
- Term
- 40 mo
- Funded
- Jan 2021
- Outcome
- Deed in lieu · principal recovered
Loans shown were originated and funded by Matador Lending LLC, Matador Note Fund 1 LLC, and affiliates between 2019 and 2024. Figures cover the Texas portfolio and are not audited fund performance. Borrower names and street addresses are withheld. Recovery of principal in a foreclosure or deed in lieu depends on collateral value and market conditions at the time, takes months, and is never assured — two of the five workouts did not return principal in full. Individual loan outcomes vary. Past performance is not indicative of future results.
What we lend on, and how we underwrite it.
Short-term, business-purpose loans secured by real estate, in Texas only — one of the country’s strongest housing and population-growth markets, and the market this team has underwritten in for twenty years.
Fix & flip
Short-term financing to acquire and renovate non-owner-occupied residential property.
Bridge loans
Interim capital for acquisitions or recapitalizations ahead of a sale or refinance.
New construction
Ground-up residential construction, advanced against as-completed value with documented draws.
Multi-family & commercial
Select loans on apartments, retail, office, industrial, and self-storage.
Entitled land
Conservative financing on entitled, unimproved land at the lowest LTVs in the book.
Disciplined sizing
No single loan exceeds 20% of fund capital once the fund holds $20M+, limiting concentration.
| Collateral type | Target LTV | Maximum LTV |
|---|---|---|
| Single family (non-owner-occupied) | 75% | 85% |
| Multi-family | 65% | 70% |
| Commercial | 65% | 75% |
| Ground-up construction (as-completed) | 75% | 80% |
| Raw land (entitled) | 55% | 65% |
Every loan clears two tests
- Borrower. Demonstrated experience in that asset class, clean background and credit review of guarantors, financial strength behind the guarantee, and a clear short-term exit — sale or refinance.
- Collateral. First-lien position with verified seniority, independent valuation, conservative LTV for the property type, title insurance naming the fund, documented budgets, and ongoing site inspections.
Portfolio weighted-LTV target 65–75%, portfolio maximum 85%. Loans generally run 6–24 months, typically interest-only with a balloon at maturity, repaid when the borrower sells or refinances.
Clear terms, paid quarterly.
Transparency is part of risk management. Here is exactly how the fund is structured. The Private Placement Memorandum governs in all cases.
| Preferred return | 8% per year, non-cumulative, paid quarterly to investors before any manager profit share |
|---|---|
| Profit split above preferred | 60% to investors / 40% to the manager, of excess distributable cash |
| Target total return | 8–12% annually — a target objective, not a guarantee |
| Asset management fee | 2% per year on invested capital |
| Offering size | $5,000,000 |
| Minimum investment | $50,000 |
| Distributions | Quarterly — elect cash, or reinvest to compound |
| Lock-up | 24 months from your investment date |
| Redemptions | After lock-up: written request with 90 days' notice; processed quarterly at up to 25% of your balance per quarter, subject to fund liquidity |
| Fund structure | Open-ended; no fixed maturity date |
| Security | First-lien loans secured by real property; 65–75% weighted portfolio LTV target, 85% maximum |
| Leverage | The fund may use a credit facility within the limits described in the PPM. Leverage can amplify returns and losses alike. |
| Eligibility | Accredited investors only (Reg D, Rule 506(c)); accredited status independently verified |
| Tax reporting | Schedule K-1 issued annually |
| Retirement accounts | Self-directed IRA eligible — confirm process and UBIT treatment with your custodian |
Distributions are not guaranteed and are subject to the fund’s available cash and the manager’s discretion, as described in the PPM. Terms summarized here are qualified in their entirety by the PPM, Operating Agreement, and Subscription Agreement.
What could go wrong.
Any manager who won’t tell you this isn’t worth your capital. These are the real risks of lending against real estate, and how the fund is built to absorb them.
The honest summary: this is a private, illiquid, non-guaranteed investment that pays a premium precisely because it is those things. It belongs in a portfolio as an income allocation you can leave alone for years — not as an emergency fund, and not as your only holding.
- Borrowers default. Some will — five of the manager's sixty Texas loans did. Each took months of enforcement to resolve, and two of the five did not return principal in full. Recovery depends on foreclosing and selling the collateral, which costs time and money. Conservative LTVs and first-lien position are what stand between a default and a loss of your principal, and they will not work every time.
- Real estate values fall. A sharp decline in Texas property values compresses the equity cushion beneath every loan in the book.
- Your capital is illiquid. 24-month lock-up, then 90 days' notice, then quarterly redemptions capped at 25% of your balance and subject to fund liquidity. Do not invest money you may need.
- Distributions aren't guaranteed. The 8% preferred return is non-cumulative and paid only from available cash. A weak quarter can mean a reduced distribution that never gets made up.
- Leverage cuts both ways. A credit facility can raise returns in good conditions and deepen losses in bad ones, and the lender gets paid before you do.
- The fund has limited operating history. Matador Note Fund 1 LLC has funded loans since 2019, but as a pooled vehicle raising outside capital it is new. The manager's lending record is real; the fund's audited performance as a fund is still being built.
- Key-person dependence. The strategy relies heavily on the manager's underwriting judgment and relationships.
Your questions, answered.
Everything a careful investor asks before subscribing. The PPM governs in all cases.
What is Matador Note Fund?
Matador Note Fund 1 LLC is a Texas limited liability company that pools capital from accredited investors to make and acquire short-term, first-lien loans secured by Texas real estate. Borrowers pay interest; investors receive an 8% preferred return distributed quarterly, plus 60% of distributable cash above that preferred return.
What is the minimum investment?
$50,000. The manager may accept a higher or lower amount at its discretion.
What return can I expect?
The fund pays an 8% non-cumulative preferred return per year, distributed quarterly, before the manager receives any profit share. Above the preferred, excess distributable cash is split 60% to investors and 40% to the manager — a target total return of 8–12% annually.
Targets are objectives, not guarantees. Actual results depend on loan performance, borrowing costs, deployment pace, and defaults. You could receive less, and you could lose principal.
How long is my money locked up?
The fund is open-ended with no fixed maturity. Your capital is subject to a 24-month lock-up. After that you may submit a written withdrawal request with 90 days' notice; redemptions are processed quarterly at up to 25% of your balance per quarter, subject to fund liquidity.
How is my investment protected?
Every loan is secured by a first lien on real property at conservative loan-to-value ratios — a 65–75% weighted portfolio target with an 85% maximum — supported by independent valuations, title insurance naming the fund as insured, documented draw budgets, and site inspections. If a borrower defaults, the fund can pursue the collateral to recover capital.
No investment is risk-free. Foreclosure takes time and costs money, and a decline in property values erodes the cushion. You could lose principal.
Who can invest?
Accredited investors only, as defined under Rule 501 of Regulation D. Because this is a Rule 506(c) offering, we are required to verify your accredited status — typically through a third-party verification service or a letter from your CPA, attorney, or registered investment advisor.
Can I invest through my IRA?
Fund interests are generally eligible for self-directed IRAs. Because the fund may use leverage, confirm the process and any unrelated business income tax (UBIT) considerations with your custodian and tax advisor before subscribing.
Can I reinvest my distributions?
Yes. You may elect to receive distributions in cash or reinvest them to compound, and change that election with 30 days' notice.
What fees does the manager charge?
A 2% annual asset management fee on invested capital, plus 40% of distributable cash above the 8% preferred return. The manager and its affiliates may also earn customary loan fees from borrowers — origination and processing fees — as detailed in the PPM.
How is the fund taxed?
The fund issues a Schedule K-1 annually. Income from lending is generally ordinary income rather than capital gain, and there is no depreciation shelter as there would be in an equity real estate deal. Talk to your tax advisor about your specific situation.
Does the manager have skin in the game?
Structurally, yes, and operationally too — the manager has been lending its own and affiliated capital in these markets since 2019. The manager earns its 40% profit share only after your 8% preferred return has been paid in full — if the fund underperforms, the manager's upside is the first thing to disappear. Separately, borrowings under any fund credit facility are personally guaranteed by the principal, for which the PPM provides a 1% guarantor fee, so the manager carries personal liability on the fund's debt.
How do I get started?
Book a 15-minute call or request the investor package. From there: verify accredited status, review the PPM, Operating Agreement, and Subscription Agreement in the data room, ask every question you have, then subscribe and fund electronically.
Two ways to start. Both take a minute.
Book a call to ask the manager anything directly, or request the investor package and read first. Open to accredited investors only — no obligation either way.